A Quarter-Century of Electrical Transformations
It’s hard to believe that the last time I sat down to write an EC&M anniversary retrospective was 25 years ago. In 2001, we celebrated our 100th anniversary with a special report on “A Century of Editorial Excellence.” With research from our entire editorial team, I put together a decade-by-decade look at the most important and memorable issues affecting the electrical industry as reported in the pages of EC&M (and its earlier iterations) over the previous century. This November, we celebrate another milestone: 125 years of covering the electrical industry. As I reflect on the last quarter of a century, so much has changed for me personally and professionally — and the same can certainly be said for the electrical professionals we are serving. So 25 years should be much simpler to summarize than 100, right? As soon as I started my research this time around, I immediately realized that wasn’t the case.
Why was this task so difficult? Because the electrical industry of today looks remarkably different from the one EC&M was covering at the turn of the 21st century. After considering the unprecedented changes that have reshaped the work of electrical professionals over the last 25 years, I immediately identified far more industry-changing developments than I could possibly cover in one article. That prompted me to choose the top five transformations I believe have had the greatest impact on the EC&M audience from 2001 to 2026.
Before we get into the top five, it’s important to mention some of the other breakthroughs that were undeniably significant. Some happened gradually; others seemed to materialize almost overnight.
Although the practice technically began decades earlier, around the early 2000s, electrical contractors began seriously looking at prefabrication and modularization to boost labor productivity, moving increasing amounts of electrical work from the job site into controlled assembly environments. By 2026, this practice, which had once faced serious resistance and a fair amount of skepticism, has evolved into an industry norm — if not an expectation.
Building automation, another trend that had been gaining steam for decades, entered a period of complete building-control integration in the 2000s. In fact, connectivity (especially that related to lighting & control devices), IoT sensors, cloud platforms, and data analytics capable of collecting and sharing enormous amounts of data transformed automated buildings into “intelligent” or “smart” buildings during this time.
Electrical maintenance also took on greater importance, culminating in NFPA 70B’s historic transition from a recommended practice to a standard effective Jan. 16, 2023. Prior to this, NFPA 70B had been in place as a recommended practice for about 50 years. This change shifted the “should” language to mandatory “shall” requirements.
Beginning in 2020, when the COVID-19 pandemic disrupted projects and supply chains worldwide (causing ongoing electrical equipment shortages, lead-time delays, and material price increases), electrical professionals were forced to rethink everything from job-site practices to when and how critical equipment is specified and ordered. With many electrical contracting companies and electrical design firms forced to adopt at least a hybrid work-from-home model, this period fundamentally changed procurement and project planning approaches on electrical job sites. Virtual meetings became second nature, and companies scrambled to find creative ways to adapt to the environment, many of which are still being used today.
Last but not least, the relentless shortage of skilled labor (qualified electricians, journeymen, foremen, electrical engineers, project managers and other skilled electrical workers) has undoubtedly been one of the industry’s greatest business challenges for the past 25 years. In fact, for more than five years, survey results from both EC&M’s Top 50 Electrical Contractors and Top 40 Electrical Design Firms have indicated that “difficulty finding and retaining quality employees” is the No. 1 factor having the most negative impact on business growth. Additionally, more than 80% of survey respondents have reported facing labor shortages over the last several years. Solving (or at least dealing with) the skilled labor shortage has become a way of life for the EC&M audience with no end in sight as more electrical professionals reach retirement age and leave the industry. Finding innovative ways to recruit and retain the next generation of electrical workers has become a puzzle every electrical firm owner is racing to solve.
Although those developments tell a remarkable story, the five transformations outlined below have had an even more profound impact on the industry in my opinion — and on the electrical professionals EC&M has educated and supported over the past 25 years. Our archives captured the early questions, emerging technologies, industry concerns, predictions, and turning points — sometimes years before anyone could know just how significant they would become. Looking back at our coverage provides a unique view of just how far the electrical industry has come in 25 years and offers some clues as to where it may be headed next.
Data center boom and AI explosion
If there’s one market that defines how dramatically the electrical industry has changed over the past 25 years, it’s data centers. Although the first mainframe “computer rooms,” considered a precursor to the modern data center, came on the scene in the 1940s, Internet data centers emerged in the mid-1990s, followed by the many iterations of data centers that followed in the early to mid-2000s.
What’s fascinating is that EC&M was covering this “power problem” from its inception. In “Powering an Internet Data Center,” which originally appeared in EC&M’s sister publication Power Quality in February 2001, Alan Katz explored how rapidly increasing Internet use was driving equally significant demand for high-quality, uninterrupted power and putting new pressure on an already stressed electrical grid. “As the Internet continues toward its ultimate destiny, its criticality and reliability will continue to take on new importance,” he wrote. “Power quality is the number one issue affecting Internet reliability today. The critical power system requirements of typical Internet data centers are increasing almost exponentially, along with the consequences of a power interruption.”
He went on to advise electrical engineers to evaluate power system topologies from the standpoint of expandability and reliability to best position themselves and the industry to configure the next generation of Internet data centers. As computing needs expanded, the electrical challenges intensified as well.
By the mid- to late 2000s, EC&M’s coverage increasingly focused on rising server densities, heat loads, cooling, power consumption, redundancy, and energy efficiency. In 2008, Russell Shetler’s “Powering Change in the Data Center” examined how greater server density was driving higher power consumption and circuit demand, essentially reshaping the data center landscape. Later that year, EC&M reported that data centers could consume 10 to 100 times more energy per square foot than a typical office building, according to research from the U.S. Department of Energy and Lawrence Berkeley National Laboratory.
At the same time, speed-to-market became critical. In 2011, EC&M reported that modular designs were beginning to replace giant data center “cathedrals.” Staff Writer Beck Ireland’s 2012 “Modular Data Center Design Trends” article traced containerized data centers back to Sun Microsystems’ 2006 Project Blackbox. By 2014, the technology had matured enough to earn its way into the most recent update of the National Electrical Code. In his June 2014 article, “The Ins and Outs of Modular Data Centers,” Electrical Consultant Mark Lamendola explained the new NEC requirements of Art. 646 and why they were important for EC&M readers to understand.
Throughout this transition period, data centers were becoming an increasingly important source of work for our readers. EC&M’s annual Top 50 Electrical Contractors surveys documented that rise clearly. By 2022, data center/mission-critical construction had ranked among respondents’ top two hottest markets for six consecutive years, even powering through the COVID-19 downturn. One contractor interviewed for the Top 50 special report even went so far as to call the data center market “recession-proof” — a prediction that certainly appears to have held true so far.
Then came the surge of artificial intelligence (AI). After the launch of ChatGPT in late 2022, everything changed. This historic milestone triggered an explosion of generative AI and large language model usage in the mainstream population, prompting the electrical industry to reimagine the traditional data center into what we now call “AI factories.”
According to Head of Content for Electrical Wholesaling magazine Jim Lucy in his February 2025 Market Watch column, the double-digit growth of data center construction continued to drive the industry: “The explosive growth in data center construction and the related increases in the demand for the electrical construction materials, contractor installation, and design services they require is quite unlike anything the electrical construction industry has ever seen.” In fact, census data cited in his article showed data center construction spending up 43.1% to $31.5 billion through November 2024, while some individual projects were topping $10 billion.
By April 2026, Amy Fischbach’s “Opportunities and Obstacles in the AI Data Center Market” documented rapidly increasing power density, grid constraints, on-site generation, and new cooling approaches as facilities traditionally designed around 25MW to 50MW gave way to 100MW- to 200MW-scale facilities, with some campuses exceeding 500MW. A few months later, a news release from Associated Builders and Contractors (ABC) noted that July’s increase of 0.1% in nonresidential construction spending was “entirely due to data centers.”
So while the scale has changed dramatically since EC&M first wrote about powering Internet data centers in 2001, the fundamental challenge hasn’t. The new digital frontier runs on electricity, and the EC&M audience (electrical professionals who design, install, and maintain the electrical equipment that powers our world) will ultimately be tasked with keeping it running every step of the way.
From 2D Drawings to Digital Construction
Twenty-five years ago, electrical design and construction still typically revolved around 2D drawings, paper plans, and field coordination. Over the next two decades, building information modeling (BIM) fundamentally changed that process, giving electrical contractors and engineers the ability to design, coordinate, and build projects in a virtual environment before going into the field.
Although some initial adopters began moving toward 3D modeling in the early 2000s, the majority of firms were a little slower to implement the technology. After Autodesk unveiled Revit Systems in March 2006, things started to change.
In “The Future Is Now,” written by Beck Ireland in September 2008, an executive interviewed for the Top 50 Contractors special report noted that BIM had only recently become an industry-wide practice. “We began implementing BIM for our own internal benefit,” said David Morris, director of virtual construction for EMCOR Construction Services. “[External] acceptance at first was rather tenuous.”
According to Morris, the tipping point occurred in mid-2007. “There was a shift from BIM and 3D modeling being an option to it being a requirement,” he said. “Over time, it’s evolved into an industry-wide acceptance.”
In March 2009, James Bratton, engineering manager, virtual design and construction for Dynalectric Los Angeles (a subsidiary of EMCOR), penned a thought leadership piece in EC&M on “Making the Transition from CAD to BIM.” Reflecting on his company’s experience, he explained that in 2002 the company’s Los Angeles branch began evaluating what was then termed “Building Systems,” which later became known as AutoCAD-MEP, as interest grew among owners and general contractors. Over the following six years, he revealed that the firm developed accurate, real-world models of more than 4,000 electrical system components by taking each piece and modeling it in 3D. “It is as accurate as if it were installed on the job site,” he said.
In November 2010, another article from Beck Ireland noted that results of a 2009 survey funded by the National Electrical Contractors Association (NECA) found that 20% of electrical contractors (36 out of 184 responding companies) were already using BIM technology. Of that group, 92% had used BIM technology in 10 or fewer projects.
Electrical design firms saw the transformation coming as well. In EC&M’s 2009 Top 40 Electrical Design Firms survey, respondents overwhelmingly named BIM as the technology most likely to radically change electrical design in the years ahead — even ranking it above renewable energy, smart grid technology, LEDs, and wireless systems. Looking back 17 years later, I must say our readers nailed that forecast.
BIM adoption wasn’t without obstacles, however. Early tools were developed largely with architects and mechanical trades in mind, leaving electrical contractors to create their own libraries and workarounds. In the 2010 article “Growing Pains,” Beck Ireland explains that despite the increase in BIM’s adoption, the electrical industry was still experiencing barriers with the technology, including limited electrical content, slow software performance, compatibility problems, and prohibitive costs, such as the expense of library development. According to one source interviewed for that article, Joe Davis, P.E., LEED AP, CEO of Custom Engineering, mechanical and electrical subcontractors had two choices when it came to adopting BIM software and processes: bring BIM in-house or outsource it.
According to the McGraw-Hill SmartMarket Report, “2009 Building Information Modeling Study,” also discussed in that article, subcontractors had a more difficult time absorbing the costs of adoption than general contractors. “It’s expensive if it’s their first project, or they don’t do very many projects that use BIM,” said Davis, who estimated the first year of BIM adoption could cost a firm around $80,000. Based on the discussion in the article, the costs include $6,000 for the software, $4,000 for hardware (at least one high-performance computer), and around $60,000 to hire the BIM coordinator. In addition, it can cost around $10,000 and take up to three years for the coordinator to build the objects library.
By January of 2014, Freelance Writer Amy Fischbach warned that contractors who didn’t embrace BIM could begin losing work as clients increasingly required BIM deliverables in “Five Ways to Unleash the Power of BIM.”
“Soon firms who do not use BIM will not be able to win jobs as more and more clients and contractors are requiring BIM deliverables for their projects,” said John T. Grady II, the corporate BIM manager for CRB who was interviewed for this piece. While more contractors, engineers, and subcontractors may be using BIM on job sites nationwide, the majority of these firms are just scratching the surface of this technology, said Darin Marsden, director of virtual construction for Faith Technologies Incorporated (FTI).
As the years progressed, BIM had expanded from the office to the field. The article “Putting BIM Technology to Work in the Field” provided a striking measure of that transition. Written by Rosendin’s Fred Meeske, corporate BIM director, and Jad Chalhoub, technology implementation lead, this article demonstrated how Rosendin’s BIM department expanded from just six employees in 2012 to more than 200 by 2019. Chronicling the company’s pilot program, the authors dove into their solution, which placed the BIM model in space at full scale using AR to visually compare the model to its potential placement.
Today, BIM is part of a much broader digital construction ecosystem encompassing virtual design and construction (VDC), prefab, AR/VR, digital workflows, and increasingly artificial intelligence. In June 2024, EC&M asked the logical next question in Tim Kridel’s “Is AI the Future of BIM?” Although the pace at which AI is driving change borders on mind-boggling, BIM technology may be equally fluid. “In the next 10 years, AI will transform the industry more than anything has in the past 100 years,” said James Barrett, vice president and chief innovation officer at Turner Construction. “I think that applies to revolutionizing BIM as well.”
Obviously, only time will tell how — and to what extent — AI will improve electrical design by automating repetitive tasks, evaluating design options, and allowing engineers to interact with BIM tools using everyday language. But one thing is certain: Realizing that potential will require better-organized data, improved software compatibility, and accessible manufacturer product information. Stay tuned for the next 25 years.
The LED Lighting Revolution
Few technologies covered by EC&M have transformed the electrical industry as dramatically over the past 25 years as the emergence of light-emitting diodes (LEDs). Although the first visible-light LED (red) was invented in 1962, it wasn’t until the early 2000s that this technology started to gain traction in commercial applications. EC&M was documenting this transformation every step of the way.
In the 2002 piece “Understanding LED Technology,” longtime EC&M lighting subject matter expert Joe Knisley revealed that LEDs were only beginning to be seriously considered for general-purpose lighting. At that time, significant hurdles remained, including high costs of adoption, efficacy, color consistency, reliability, lumen maintenance, and the need for more industry standards. “First used as status and indicator lamps — and more recently in under-shelf illumination, accent lighting, and directional marking applications — high-brightness LEDs have emerged within the last six years,” he wrote. “But only recently have they been seriously looked upon as a feasible option in general-purpose lighting applications.”
Six years later, the conversation was changing. In his 2008 Industry Viewpoint, Editor-in-Chief Mike Eby maintained that solid-state lighting was approaching a “tipping point” for widespread adoption. Knisley, who attended the Lightfair Show every year in person and covered it for the magazine, also documented improved efficacy and color along with growing use of LEDs for street, parking, architectural, and other applications in his 2008 Field Report.
The transformation continued to accelerate. From 2010 to 2015, LED adoption increased significantly as efficiency and performance improved, costs declined, and legacy technologies (incandescent and fluorescent) continued to lose market share. According to U.S. Department of Energy research, LEDs accounted for less than 1% of the nation’s installed lighting inventory in 2010, increasing to 8% by 2015 and approximately 48% of residential and commercial lighting installations by 2020.
In Steven Bellwoar’s 2010 feature article, “LEDs’ Dirty Little Secrets,” things were still relatively unsettled in the market. Although he admitted LED technology had reached its potential for almost any lighting application, Bellwoar warned the EC&M audience of the real-world challenges that existed and walked them through challenges his firm, Colonial Electric Supply, had faced on recent projects. “LEDs claim many advantages over traditional lamps (i.e., incandescent, HID, and fluorescent), namely durability and longevity. Despite these benefits, the most obvious challenge with LED lighting is its high initial purchase price tag — a reality that undoubtedly stems from its newness to the market. Like all new technologies, however, the cost is expected to eventually decrease to a more competitive level.”
Citing a record number of attendees (more than 24,000) at the 2012 Lightfair show, Knisley offered a striking snapshot of the changing market in his post-show piece. Linear fluorescent lamps still accounted for roughly 80% of lamps used in the commercial sector, but LEDs were so prevalent on the show floor that EC&M suggested the event could almost have been called “LEDfair.”
Economics helped turn the tide. Utility rebates and government incentives helped offset LEDs’ higher upfront costs as efficiency improved and prices fell. According to DOE research in its “Adoption of Light-Emitting Diodes in Common Lighting Applications,” approximately 49 million LED lamps and luminaires were installed across nine major applications in 2012, generating an estimated $675 million in annual energy savings. By 2014, DOE was projecting LED lighting’s share of sales, measured in lumen-hours, would grow from just 3% in 2013 to 48% by 2020, according to its report on “Energy Savings Forecast of Solid-State Lighting in General Illumination Applications.”
EC&M’s lighting coverage reflected both the excitement and growing pains. Tom Zind’s 2015 feature “LEDs Still a Mystery to Many Contractors” described a rapidly expanding but sometimes “Wild West” market in which contractors still had to navigate inconsistent product quality, performance, and reliability. That same year, Mike Eby outlined the confusion that still existed on the LED front among “the rank and file of electrical designers, maintenance personnel, and electrical contractors.”
As of 2016, a report from the U.S. Department of Energy (DOE) prepared by Navigant found that 874 million of the lighting systems installed through that year in the United States were LED, which captured only 12.6% of the market that year. However, as the years passed, EC&M started naming LEDs as the first choice for many new construction and renovation projects — the revolution was on as LEDs continued to turn lighting into a digital platform. Knisley documented this trend in his 2017 Lightfair report, noting that sensors and networked controls were now capable of asset tracking, space utilization, indoor positioning, and integration with HVAC and building management systems. In 2018, Focal Point’s Matthew Blakeley wrote about how connected luminaires could become data collection and smart-building management platforms in “Welcome to the Connected Lighting World.”
By the 2020s, LEDs had earned a place in the market, dominating many general lighting applications with connected lighting, advanced controls, and smart building integration expanding their capabilities. According to Industry Expert Tony Adams in his 2021 piece on “The Evolution of Controls Technology,” the lighting industry had successfully transitioned from legacy sources to LED in a little over a decade.
By 2023, to say that LEDs dominated the commercial and industrial lighting market would be an understatement. By that time, first-generation LED installations were already reaching replacement age, creating an opportunity to pair the next generation with networked lighting controls.
Few pieces sum up the impact LEDs have had on the electrical industry as well as Liesel Whitney-Schulte’s article on “The Wonderful, Widening World of LEDs” published in 2024. According to the author, DLC program director, lighting used to account for the largest share of electricity consumption in U.S. commercial buildings. “In 2003, the average was 38%, but thanks to widespread energy-saving LED technology, lighting’s share fell to 17% by 2017,” she wrote. “As adoption of LEDs expanded, energy use dropped to 10% in the US Energy Information Administration’s most recent Commercial Buildings Energy Consumption Survey (published in 2022 based on 2018 data).”
Today, the question is no longer whether LEDs will replace legacy lighting. EC&M’s coverage has moved on to the next challenge: pairing LEDs with networked controls and connected building systems to extract even greater energy savings, intelligence, and value from the humble light fixture as well as how AI will affect the connected lighting space.
Arc Flash Safety Strides — from PPE to Prevention
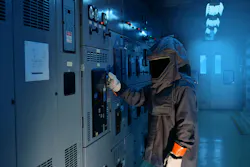
Few developments over the past 25 years have changed electrical work as profoundly as the industry’s evolving understanding of arc flash hazards. When it comes to arc flash guidance, a major turning point came with the 2002 National Electrical Code (NEC). In this edition, Sec. 110.16 introduced arc flash warning label requirements that required certain electrical equipment to be field marked, warning qualified workers of potential arc flash hazards. EC&M’s coverage during this period helped explain what the new requirement meant in practice: Basically, a warning label alone couldn’t protect a worker. Facilities needed to understand the hazard, calculate potential incident energy, provide appropriate PPE and training, and establish safe work practices.
Read more about this development in NEC Consultant Paul Abernathy’s “25 Years of NEC Changes Through My Eyes.” “Suddenly, the question was not simply whether an overcurrent protective device would clear a fault, but how quickly it would clear it — and how much energy could be released before it did,” notes Abernathy. As he explains in the article, this was a major change in the way electrical professionals perceived protection for commercial and industrial electrical systems.
In September 2002, almost immediately following the changes in arc flash warning labels, IEEE 1584, IEEE Guide for Performing Arc-Flash Hazard Calculations, provided an increasingly important method for calculating arc flash incident energy that gave engineers a more sophisticated tool for evaluating potential hazards. Major changes in NFPA 70E, “Standard for Electrical Safety in the Workplace,” came soon thereafter with its 2004 update.
EC&M characterized changes in that edition as significant because they moved safety-related work practices to the forefront, emphasized working on energized parts as a last alternative, and introduced energized electrical work permits. Beck Ireland covered revisions to the 2004 standard in “NFPA 70E: Revising the Standard” in May 2008. In that piece, she noted that what was then the seventh edition of the standard included several significant revisions, including an emphasis on safe work practices, a name change to the current title, and reformatting to comply with the NEC style manual, which gave a unique designation for each requirement.
It wasn’t long before terms such as “incident energy,” “flash protection boundary,” and “arc-rated clothing” became part of the everyday safety vocabulary of electrical professionals.
Biz Com Electric’s Larry Ayer, P.E., explained that and more in “Keys to Understanding NFPA Standard 70E,” which ran in May 2005. “Operating protective devices, testing for voltage, and installing or removing breakers are common tasks that offer the possibility of an arc flash injury,” he wrote. “That’s why it’s imperative that you and your workers understand the requirements of NFPA 70E as much as you understand the NEC. This means having a clear understanding of how various fault-current levels affect the HRC rating on a system.”
EC&M spent much of the early to mid-2000s helping readers understand how arc flash studies, equipment labeling, incident-energy calculations, and PPE all worked together to reduce arc flash hazards. Although much of the industry’s initial response centered on PPE, many quickly learned that you can’t simply “dress” your way out of an arc flash hazard.
In the 2007 article “Calculating Arc Flash Energy Levels,” Benjamin Medich of Ballinger reiterated this shift in mindset. “While not a major topic of consideration when designing and maintaining facilities in past years, code-enforcement bodies have become increasingly aware of the danger of arc flash incidents associated with working on live electrical gear,” he wrote. “As a result, facility managers and their consulting engineers are paying more attention to arc flash analysis.”
Author John Kolak made that point in EC&M’s 2010 “Arc Flash Hazard Analysis Primer,” explaining that the goal of an arc flash analysis wasn’t merely to determine which flame-resistant clothing workers should wear. “Many electrical engineers have used the methodologies discussed in this article to calculate the ‘heat’ associated with electric arcs, but then used that information only to recommend electrical workers wear higher levels of FR clothing when performing energized work,” he wrote. “The appropriate approach would be to first exhaust reasonable attempts to make engineering changes to the system to reduce the ‘heat,’ and then select the appropriate FR clothing for the risk that cannot be adequately controlled through engineering interventions.”
By 2011, EC&M was walking readers through IEEE 1584 calculations and explaining why generic warning labels weren’t enough to communicate incident energy, boundaries, and PPE requirements, as explained by Frank Mercede and Joseph Mercede of Mercedes Electric Co., Inc., in the article “Arc Flash Calculations Clarified.”
The philosophy continued to evolve over time. As explained by Tommy Northcott, P.E., of Jacobs Technology in “Arc Flash Risk Assessment Considerations,” the 2015 edition of NFPA 70E shifted terminology from “hazard assessment” to “risk assessment,” expanding the focus from how severe an arc flash event could be to both its severity and the likelihood that it would occur. The 2018 edition placed even greater emphasis on risk. “Any task that has the potential to involve an electrical hazard must include an arc flash risk assessment from inception. The overall goal of the assessment is to encourage a deliberate thought process that allows qualified electrical workers an opportunity to determine feasible means to avoid exposure to an arc flash hazard,” he wrote. “If the assessment determines that the potential arc flash hazard exposure cannot be avoided, the assessment process facilitates a logical method for determining preferred means to protect the workers from arc flash hazards. While this process may seem tedious at times, the habits that are developed through following this process consistently may indeed prevent unimaginable pain and suffering caused by experiencing an arc flash event with insufficient protection.”
The hierarchy of controls reinforced another major change in thinking: PPE should be considered the last line of defense — not the first. Whenever possible, eliminate the hazard by establishing an electrically safe work condition. When that isn’t possible, engineering and administrative controls, equipment design, maintenance, training, labeling, and appropriate PPE (now at the bottom of that hierarchy) all become part of the safety equation. Today, arc flash safety is woven into electrical system design, maintenance, studies, training, work practices, and equipment selection in ways that would have been unfamiliar to many electrical professionals at the turn of the 21st century.
In November 2024, OSHA released its first major update to arc flash hazard guidance in nearly 20 years, emphasizing the importance of appropriate arc-rated PPE and addressing misconceptions about working on de-energized equipment. As NFPA’s Corey Hannahs outlined in his May 2025 EC&M article, “Making Sense of OSHA’s New Arc Flash Hazard Guidance,” the recommendations reinforced the need to verify an electrically safe work condition and properly protect workers from arc flash hazards, although the guidance itself did not establish new regulatory requirements
Looking back, the industry certainly made significant strides when it comes to arc flash safety in the last 25 years. Perhaps the biggest transformation, however, lies in the fundamental shift in how our readers think about energized electrical work in the first place.
Electrification Reshapes Electrical Infrastructure
At the turn of the 21st century, the electrical industry was already beginning to explore alternatives to the traditional utility-supplied power model because concerns about aging infrastructure, reliability, rising electricity demand, and the limitations of the existing transmission system had become too difficult to ignore.
According to the American Society of Civil Engineers (ASCE) 2025 Report Card for America’s Infrastructure, the U.S. electrical grid is in dire need of an overhaul. Three stats from this report demonstrate the urgency of modernization efforts: 70% of U.S. transmission lines are 25 years old or older; 70% of power transformers are at least 25 years old; and 60% of circuit breakers are 30 years old or older. Although obviously important, grid modernization and electrification aren’t exactly the same thing, so let’s take a look at three key periods that marked the evolution of this electrification journey. Unlike the LED lighting revolution, which basically replaced one technology with another, this transformation necessitated a complete reimagination and expansion of the existing electrical grid into avenues never thought possible decades before.
The early 2000s exposed aging infrastructure and the need for grid modernization (one memorable milestone during that time was the massive Northeast blackout of 2003 that affected approximately 50 million people in the United States and Canada). The goal here was to make existing electrical systems more reliable, resilient, and efficient. The 2010s brought rapid growth in renewable generation and new technologies (solar, wind, EV charging, microgrids, and battery storage), changing how electricity could be generated, stored, and distributed. By the 2020s, expanding electrification (namely the growth in electric vehicles and electric heating) was placing additional demands on an already strained grid, requiring infrastructure to accommodate not only new sources of power but also an expanding range of increasingly demanding electrical loads.
EC&M’s coverage of these core areas was spot on as ideas became reality. In the September 2001 article “Solar Biz,” EC&M’s sister publication CEE News documented how electrical contractors were finding new business opportunities in solar installations as rising electricity costs and concerns about power reliability were driving interest in alternative energy sources. By February 2004, EC&M was offering readers advice on “How to Launch a Solar-Powered Electrical Contracting Business.” In this piece, longtime Freelance Writer Amy Fischbach highlighted opportunities in photovoltaic (PV) installations and distributed generation by showing what companies (Alternative Energy Solutions in Stamford, Conn., and Warmack Electric in Anaheim, Calif.) had done to capture a share of this growing market.
As these technologies gained traction, new challenges emerged, particularly when it came to connecting distributed generation to the utility grid. By 2009, EC&M was examining the complexities of differing state interconnection requirements, foreshadowing the increasingly complicated electrical infrastructure that would emerge over the following decade. In “Understanding How Each State’s Interconnection Standards for Distributed Generation Installations Differ,” Beck Ireland broke down the technical challenges of integrating distributed generation into a grid originally designed for one-way power flow. “Until recently, a major barrier to the widespread adoption of grid-connected cogeneration and small power production, otherwise known as distributed generation (DG), in the United States has been the inconsistent implementation of codes, standards, and regulations,” she wrote. “Despite a 30-year federal law requiring electric utilities to buy power from independent companies that can produce power for less than what it would have cost the utility to generate the power, there is still very little renewable energy on the grid.”
In 2010, NEC Expert Mike Holt’s “Solar Photovoltaic Systems” series helped readers navigate Art. 690 as PV installations began to accelerate across the country. That same year, Editor-in-Chief Mike Eby’s July Industry Viewpoint, “Evolution,” predicted an explosion of activity around electric vehicles and the infrastructure required to charge them. Soon thereafter, the magazine hosted a webinar posing a question that seems remarkably prophetic today: “Electric Vehicles Are Coming — Is Our Electrical Infrastructure Ready to Accept Them?” That event drew more than 750 attendees who wanted to learn more about the widespread adoption of EVs as well as how to build a national network of charging stations. But the bigger transformation came as these once-separate technologies began converging.
The following year, in April 2011, Beck Ireland’s “The Whole Package” article explored “solar franchising” and documented ways in which electrical contractors could harness solar as a new source of revenue. The numbers soon demonstrated why. In May 2012, EC&M reported in its “Solar PV Product Showcase” that U.S. PV installations grew 109% in 2011, according to the “U.S. Solar Market Insight Report” released by the Solar Energy Industries Association and GTM Research. Falling costs were helping move solar from an alternative technology toward an increasingly important source of electrical work. At almost exactly the same time, electricity was beginning to move into another enormous market: transportation.
By September 2013, Mike Holt was explaining the requirements of NEC Art. 625 for installing EV charging equipment in his article, “EV Charging Systems.”
By 2015, EC&M was reporting on electrical contractors combining solar and wind expertise with battery storage and microgrids. In fact, one leading electrical contractor, Rosendin Electric, announced the consolidation of its Renewable Energy Divisions in its Southern California office in an EC&M news brief dated May 2015, which also explained that this endeavor included battery storage and sustainable power to support the emerging microgrid market.
In 2016, we covered projects integrating PV, battery storage, controls, and microgrids to improve resiliency and even allow facilities to operate independently from the grid when necessary. The NEC was changing, too, expanding to address large-scale PV systems, energy storage systems, and DC microgrids. Energy storage then emerged as a major piece of the puzzle. Tim Kridel’s 2020 EC&M feature “Energy Storage Opportunities” examined utility-scale battery energy storage systems as a growing opportunity for electrical contractors as lithium-ion costs fell and renewable generation increased. By early 2021, EC&M was reporting that U.S. energy-storage deployments had jumped 182% in a single quarter. “More than 3.7 million electric vehicles (EVs) were sold worldwide over the past two years. That’s creating business opportunities for electrical contractors, many of which aren’t immediately obvious,” he wrote. “One case in point involves electric utility-scale battery energy storage systems (BESS), which typically use the same lithium-ion (Li-ion) technology as EVs. As EV sales grow, so do Li-ion volumes. That helps send Li-ion technology down the cost curve, making BESS more attractive to more electric utilities.”
EV infrastructure was scaling rapidly as well. What EC&M had described as an emerging opportunity in 2010 had become a national infrastructure challenge by the 2020s, prompting EC&M to launch a dedicated EV Infrastructure e-newsletter and devote extensive coverage to EVSE design, installation, Code requirements, maintenance, and the national charging buildout.
Taken together, these developments have fundamentally changed the electrical infrastructure EC&M readers design, install, and maintain. A facility can now consume electricity, generate it through solar, store it in batteries, use it to fuel vehicles, disconnect from the grid through a microgrid, and potentially send power back in the other direction.
Fast-forward to October 2026, when Amy Fischbach’s article, “Designing and Powering the Future Grid,” examined the challenges facing utilities, electrical engineers, and contractors as they work to modernize the nation’s aging electrical infrastructure. Fischbach, who is not only a longtime freelancer for EC&M but also the head of content for its sister publication, T&D World magazine, explored what’s ahead for the energy sector as electrical engineers and contractors help utilities modernize the grid while facing ongoing challenges such as infrastructure bottlenecks, prolonged timelines, and long equipment lead times. Looking ahead, technologies such as advanced conductors, grid automation, distributed energy resource management systems, and artificial intelligence are expected to play increasingly important roles in creating a more reliable, resilient, and flexible electrical grid.
Over a decade ago, EC&M asked its audience with that ground-breaking webinar whether the electrical infrastructure was ready for electric vehicles. Sixteen years later, the bigger question is whether the electrical infrastructure is ready for an increasingly electrified world.
In retrospect
Looking back over EC&M’s coverage of the electrical industry for the past quarter-century, I feel an overwhelming sense of pride in our brand’s rich heritage and 125-year legacy of serving electrical professionals. What a privilege it’s been for me to serve this fascinating industry for so many years. Just as we documented the industry’s evolution during our first 100 years (featured in our centennial issue in June 2001), EC&M has been there every step of the way as each of the transformations highlighted in this article unfolded.
Although the technologies, challenges, and opportunities facing our readers have changed dramatically since 1901, our mission has remained remarkably consistent: to deliver the trusted technical information electrical professionals need to do their jobs more efficiently, effectively, and safely. If the last 125 years have taught our editorial team anything, it’s that the electrical industry will never stop evolving — and I have no doubt EC&M will be there to document the next 25 years of innovation.
Editor’s Note: This piece was created with the assistance of generative AI tools for outlining, background research, and archive retrieval and was edited by our content team for clarity and accuracy.
About the Author
 Ellen Parson
Editor-in-Chief - EC&M
Ellen Parson is the Editor-in-Chief for EC&M. She has a journalism degree from the University of Missouri-Columbia. She's been a business-to-business writer and editor for more than 25 years, most of which have been covering the construction and electrical industries. Contact her at [email protected].